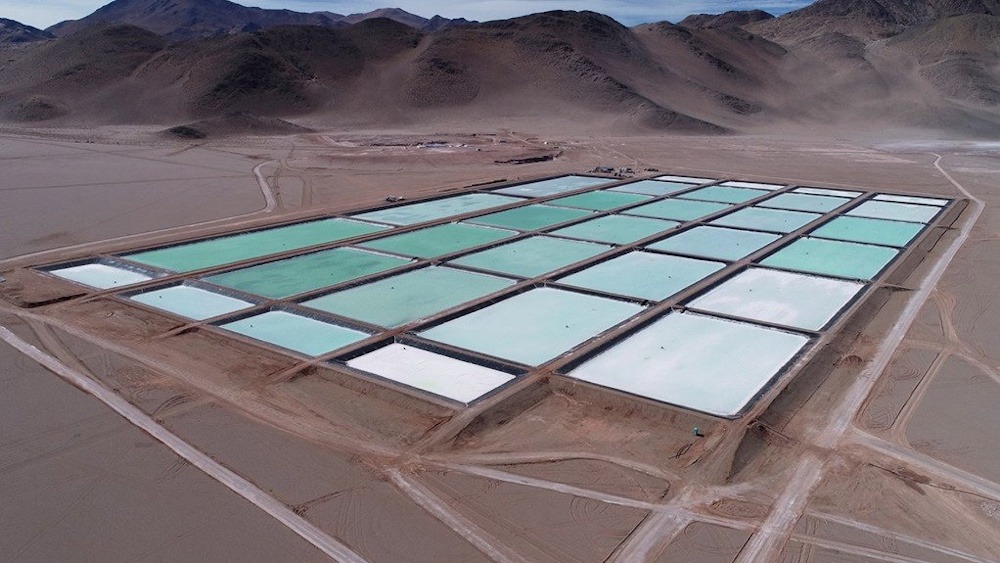
Argentina’s mining industry is witnessing a robust revival, propelled by a surge in exports and the increasing attractiveness of new ventures, especially those related to lithium and copper, alongside precious metals like gold. Argentina achieved a record in mining exports in 2025, reaching a total of US$8.1 billion, as reported by the national statistics institute INDEC. That represented a 19.2% increase from $6.8 billion the previous year. This year appears poised for even greater success. Exports from the metal mining and lithium sectors reached US$6 billion in the first half of 2026, reflecting a substantial increase of 69.7% compared to the same period in 2025. Investment is also on the rise. Of the 24 projects sanctioned under the Large Investment Incentive Regime, 50% are allocated to the mining sector, while an additional six are currently undergoing review. In this context, Argentina, Bolivia, Chile, and Peru formalised a joint declaration in late August, focusing on the attraction of mining investment and the enhancement of regional collaboration concerning critical minerals. In an interview, Francisco Balduzzi elaborated on the implications of the agreement for the region and the potential impact of regulatory and cross-border considerations on the advancement of various projects. He also highlighted the region’s “novel” geopolitical moment following increased United States engagement in Latin America, aimed at consolidating regional supply chains for critical materials.
Argentina, in particular, continues to be unappealing to certain investors due to the economic and political instability observed in recent decades, he acknowledged. Interest in the mining sector is on the rise, having already garnered significant investment. More than merely an agreement, this represents a declaration of intent aimed at enhancing the predictability of mining operations while simultaneously improving their efficiency. It does not represent a statement from the four governments asserting, “Our mining policies are heading in this direction.” It is indeed significant as it represents a public declaration from major copper-producing nations, including Chile and Peru, alongside three countries likely possessing the largest lithium reserves globally: Bolivia, Argentina, and Chile. From that perspective, its significance is substantial. What is noteworthy about the declaration is that it articulates four intentions collectively embraced by these governments: firstly, the promotion of responsible mining across all four nations and the enhancement of supply chains among them, which are already somewhat established, especially between Argentina and Chile, where a prior agreement is in effect. They also discuss collaboration on geology, engaging in research and, crucially, establishing technical working groups to tackle these matters. It serves as a signal to the global community that this opportunity is present and outlines the intended trajectory they plan to pursue.
A joint statement by the four governments holds notable international political significance for foreign investors, as it conveys that all four countries are aligned in their positions. They also allocate capital to those nations. In the Lithium Triangle, especially along the Chile-Argentina border, numerous mines are situated directly on the border. The extraction may occur on the Argentine side, whereas transportation or refining is conducted on the Chilean side, providing a clear illustration of the process. The same scenario could unfold between Peru and Chile or Bolivia and Argentina. Natural and geographical synergies exist. If one possesses a mine that spans the Chilean-Argentine border, it is advisable to avoid applying for permits independently in Argentina and Chile, given the discrepancies in their timelines. You desire to accomplish multiple tasks simultaneously. While the declaration does not explicitly state this, it is reasonable to anticipate that forthcoming efforts will focus on standardising specific procedures to ensure that cross-border projects are viable for investors. When investors evaluate a project that crosses a border, they are contemplating a unified initiative. Today, nations operate under varying legal frameworks. Argentina possesses the RIGI, while Peru features a relatively efficient permitting system. Chile is recognised for its mixed mining companies, and Bolivia is in the process of opening up. They are at varying stages, and aligning them to a more comparable level, where operations function with greater efficiency, enhances the appeal of investment.
Next, we turn our attention to the supply chain. Peru and Chile are recognised as prominent mining nations, where one would expect a greater presence of service providers in the industry compared to Argentina and Bolivia. This could facilitate the ability of those providers to extend their services to additional countries as well. Numerous potential advantages exist. I also do not believe this alone will attract investment to the region. To attract investment, it is essential to demonstrate stability. Mining projects represent long-term investments, with companies frequently allocating resources to regions characterised by instability. However, the presence of stability can significantly enhance the overall prospects of these ventures. Investor interest and signals from investors are also essential when they enter these countries to invest. It is also crucial to recognise that this issue extends beyond merely foreign investors. It pertains to fostering local industry and ensuring that an Argentine firm aiming to penetrate the Chilean market comprehends the regulatory framework. That is the pivotal question at hand. I work in energy and natural resources, and I would assert that mining is the sector where I have observed the highest influx of foreign investors, surpassing other extractive industries. Investment has begun to enter Argentina; however, it is crucial to recognise that during the 1990s, the country implemented a framework aimed at drawing in foreign investors. Over the subsequent two decades, there were expropriations and limitations on the repatriation of dividends abroad, with the notable exception of the tenure of Mauricio Macri.
Some investors entered the market in the 1990s, exited, returned during Macri’s tenure, faced losses, and remain disinclined to engage with Argentina. There exist two distinct categories of investors. The first group comprises individuals who have experienced losses and will refrain from investing until a subsequent period of stability is established. For them, that primarily signifies the president of the current administration securing reelection. In their perspective, they are contending with an Argentina that has consistently altered its trajectory. I have encountered numerous individuals, and they express a complete disinterest in the country. There exists an additional cohort of investors who express alignment with the prevailing U.S. administration. They perceive the actions of the U.S. government throughout Latin America as a novel development. The United States has adopted a more favourable stance toward Latin America than observed in recent years, prompting investors in this region to allocate capital accordingly. In my assessment, a comparison of Argentina’s oil and mining sectors reveals a greater influx of foreign investment in mining relative to oil. Argentina faces a challenge due to its longstanding negative perception on the global stage. Re-establishing that trust transcends the mere enactment of legislation. Once implemented, they must be enforced and maintained consistently over time. Something noteworthy occurred upon the announcement of the currency swap with the United States. Enquiries to my office increased significantly, as the U.S. backing of Argentina conveyed a robust signal. Some investors enter the market and attract additional participants, including those who might otherwise remain under the radar. That is a reality. Lithium underwent a significant surge, which later decelerated as prices reached a state of equilibrium. Copper was already experiencing a supply shortage prior to the energy transition and the growth of renewable energy sources.
Demand for copper is substantial. Chile and Peru are significant producers of copper, while Argentina possesses substantial potential for metal production. If Argentina achieves that stability and the United States maintains a policy akin to its current approach, it could significantly benefit the region. It is a confluence of factors; it is not solely contingent upon developments in Argentina. Investors remain a necessary presence. Argentina can execute all the right strategies, yet if another jurisdiction possesses superior geology, mining companies will inevitably gravitate toward the more favourable geological conditions. In the realm of mining, Argentina appears to be the locus of significant interest from foreign investors. Altering the prevailing perception of Argentina in its entirety is likely to be a protracted endeavour. In the mining sector, the process is already underway, and as additional investments are made, further investments are likely to ensue. If there are binational projects, securing an agreement with Chile presents a significant advantage for investors. If these initiatives materialise, investment can be executed with greater efficiency, encompassing permitting, regulations, and other domains. Argentina possesses significant potential; however, those nations have a more established history in the mining sector. Argentina encompasses more than merely its mining sector. It stands in stark contrast to those nations where mining serves as the primary commodity. Argentina, for better or worse, possesses an abundance of diverse resources.
